FaithFi: Faith & Finance

Screenshots
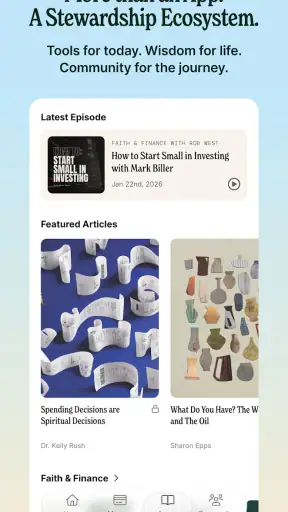
Details
- Rating
- 85.00 reviews
- Version
- 5.1.3
- Developer
- FaithFi: Faith & Finance
Analysis by Norviv
Managing money is rarely only about arithmetic. For many people, spending, saving, giving, debt, and planning are tied to personal beliefs, which is where FaithFi: Faith & Finance tries to fit. I approached it as a finance app rather than a conventional banking tool, and its central idea is easy to understand: bring faith into everyday decisions about money.
The app is developed by FaithFi: Faith & Finance and is available as a free download for Android users. It belongs to the finance category, carries an Everyone age rating, and has passed the early trial stage with more than ten thousand installs. Its average score is 3.6 from roughly one hundred sixty ratings, so the public response looks mixed rather than overwhelmingly enthusiastic. That is useful context: this is an app worth examining for its particular purpose, not one I would recommend blindly to every person looking for a budget.
How FaithFi approaches everyday money decisions
What makes this app different from a standard expense tracker is its starting point. Most finance apps begin with categories, charts, account balances, or bill reminders. FaithFi begins with the relationship between faith and financial behavior. That makes it more relevant to someone who wants money management to support personal convictions instead of treating finances as a purely technical problem.
In practical terms, I would view it as a companion for reflection and financial habits, not as a replacement for a bank application. If I needed to transfer money, check a live account balance, or manage a card, I would still turn to my bank. If I wanted a conventional spreadsheet-style budget with extensive customization, I would probably choose a dedicated budgeting service. FaithFi makes more sense when the question is not only “Where did my money go?” but also “How do my financial choices fit the way I want to live?”
That distinction matters because the app’s appeal depends heavily on personal fit. Someone who does not want a faith-based perspective in a finance tool may find the concept unnecessary. Someone who already thinks about generosity, stewardship, contentment, and responsible spending through a Christian lens may find the framing more useful than another generic pie chart.
What the free download means in practice
The app is free to download, which makes trying its approach relatively low-risk. There is also a range of optional in-app purchases, with individual items priced from $3.99 to $11.99. I would therefore separate the initial access from the full value question: installing it costs nothing, while some additional material or functionality may require payment inside the app.
That is an important distinction for anyone comparing it with free budgeting tools. A free download does not automatically mean every part of the experience is free, and the presence of paid items means I would check the purchase screen carefully before committing. The useful question is whether the free portion already supports the habit or reflection I want, or whether the paid content is the part that makes the app worthwhile for me.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would not buy anything immediately after installation. My approach would be to spend enough time with the accessible material to see whether the tone, structure, and financial perspective actually help me make decisions. If the app becomes part of a regular routine, an optional purchase may feel easier to justify. If I only open it occasionally, the free access may be sufficient.
Where the app can add value beyond a normal budget
The strongest potential value is the connection between financial action and personal intention. A typical budgeting app can tell me that I overspent in a category. It usually does not help me examine why I spent that way, whether the purchase reflects my priorities, or how generosity and restraint fit into my broader beliefs. FaithFi’s faith-centered identity gives those questions a more direct place in the experience.
That can be especially helpful when financial goals feel abstract. “Spend less” is vague. A more meaningful goal might be to create room for giving, reduce anxiety around money, or make household decisions with greater consistency. The app’s perspective can help turn those ideas into conversations and recurring habits, even if I still use another tool to record the exact transactions.
One useful workflow would be to pair FaithFi with a bank app rather than forcing it to do everything. I could review actual transactions in my bank, identify one or two decisions that deserve attention, and then use FaithFi’s faith-oriented material to think through the habit behind them. That division of labor is more realistic than expecting one app to provide banking, accounting, education, and spiritual guidance at the same time.
Another practical use is household discussion. Couples or families can disagree about spending without disagreeing about the goal of being responsible. A faith-based framework may give them shared language for talking about priorities, giving, lifestyle inflation, and financial pressure. I would use it as a conversation starter, not as an authority that settles every disagreement.
Three ways I would use it deliberately
- Weekly review: I would choose one recent spending decision, look at the motivation behind it, and write down a small adjustment for the following week rather than attempting a complete financial overhaul.
- Goal alignment: Before creating a new savings target in a separate finance tool, I would use the app’s faith-centered perspective to decide why the goal matters and what trade-off I am willing to accept.
- Shared household check-in: I would invite a partner or family member to discuss one money pressure at a time, keeping the conversation focused on values and habits instead of turning it into a blame session.
These workflows are more valuable than simply opening an app and reading passively. The non-obvious benefit is that FaithFi can serve as a bridge between financial tracking and personal accountability. It does not need to replace a detailed budget to influence the choices that a detailed budget alone may fail to change.
What I would not expect from it
I would not treat this as a complete personal-finance command center. The verified app details identify it as a finance app with a faith-and-finance focus, but they do not establish that it offers every feature found in a bank, investment platform, tax tool, or advanced budgeting service. For those jobs, I would use the specialist product designed for the task.
This matters for people who want automatic account synchronization, detailed reports, debt payoff calculations, investment tracking, or sophisticated envelope budgeting. If those functions are the main reason I am downloading a finance app, I would compare dedicated alternatives first. FaithFi’s distinctive value is its perspective, not the assumption that it replaces every other financial tool.
I would also keep the app’s guidance in the right role. Faith-based financial reflection can be encouraging, but it should not replace professional advice for complex debt, taxes, investments, legal matters, or serious financial hardship. The app may help me clarify priorities; it should not be the only basis for a high-stakes decision.
Trade-offs, audience fit, and my buying decision
I’d use this section to weigh the app’s faith-centered approach against the practical compromises that come with choosing a focused companion over an all-in-one money manager. The key question for me is whether that perspective changes a real habit, not simply whether I enjoy the material; from there, I can explain who is likely to find the trade worthwhile.
The friction points I noticed in the concept
The most obvious trade-off is specialization. The same faith-centered approach that makes FaithFi appealing to its intended audience can make it feel less relevant to everyone else. Even a strong finance tool becomes distracting if its guiding language does not match the way I think about money.
There is also a risk of separating reflection from action. I can read useful material, feel motivated, and still fail to change my spending if I do not connect the app to a concrete routine. That is why I would pair it with transaction records, a written goal, or a recurring household discussion. Without that step, the app could become something I consult for inspiration but do not use to make measurable decisions.
The average rating of 3.6 suggests that the experience has not been universally smooth for users. I would interpret that cautiously rather than treating it as a final verdict. Ratings can reflect different expectations: one person may want devotional guidance, another may expect a full budget engine, and a third may judge the app mainly on convenience. Still, the score is a reminder to test the free experience before paying for optional items.
The current version is 5.1.3, and the app supports Android devices running version 7.0 or later. That gives it a broad compatibility range for many Android users, though I would still check how it behaves on my particular device before building an important financial routine around it. For an app I expect to use regularly, stability and ease of returning to the same workflow matter as much as the initial idea.
Who is most likely to get real value
I think FaithFi is best suited to a person who already wants a Christian perspective included in financial planning and who is willing to connect reflection with action. It may also suit couples or small groups looking for a shared starting point for money conversations. The app is particularly promising for someone who has tried ordinary budgeting tools but found that categories and totals did not address the emotional or moral side of spending.
It can also work well for a beginner who feels intimidated by complex finance software. A values-first approach may be easier to engage with than a screen full of accounts, graphs, and technical terms. I would still encourage that beginner to learn the practical basics elsewhere when necessary, but FaithFi may help establish a reason to keep going.
I would skip it if I wanted a neutral, secular interface, a high-powered accounting system, or direct control over financial accounts. I would also skip paid items until I knew that the app’s content genuinely changed my routine. Someone who already has a trusted faith community, financial adviser, and detailed budget may find the app redundant unless its particular format adds something new.
A realistic everyday scenario
Imagine I notice that small convenience purchases are making it harder to save for a family goal. A standard budget can show the total, but the number alone may not explain the pattern. I could review those transactions in my usual banking or budgeting tool, then open FaithFi to think about contentment, priorities, and the kind of household habits I want to build. I might decide on one specific boundary for the next week and discuss it with my partner.
The following week, I would check whether the boundary was realistic. If it failed, I would adjust the habit instead of treating the result as a moral judgment. That is where I see the app’s best role: helping me examine the meaning behind a financial pattern while another tool handles precise records. The combination is more useful than either side alone.
My verdict on free access and paid value
My recommendation is conditional but positive. I would tell a faith-oriented friend to try FaithFi because the free download makes exploration straightforward and the app offers a perspective that ordinary finance tools usually do not emphasize. I would not describe it as the best choice for everyone, and I would not assume that an optional purchase is automatically good value.
The free experience should earn my attention before any paid item earns my money. I would use it long enough to answer three practical questions: Does it help me make a specific financial decision? Can I fit it naturally into my weekly routine? Does its faith-based approach feel thoughtful rather than repetitive or disconnected from my real situation? If the answer is yes, an in-app purchase in the listed range may be reasonable for someone who wants more from the experience.
If the answer is no, I would keep using a conventional budgeting app, a spreadsheet, or my bank’s tools and look elsewhere for faith-based financial guidance. FaithFi is not valuable because it carries a finance label; it is valuable only when its particular connection between faith and money improves the choices I actually make.
Overall, I see it as a focused companion rather than a complete financial system. Its free entry point, Everyone rating, and clear faith-and-finance identity make it easy to test, while the mixed public rating and optional purchases call for realistic expectations. For the right user, it can add meaning and accountability to ordinary money management. For someone seeking advanced financial controls or a purely practical tracker, skipping it is the more sensible decision.
Frequently Asked Questions
01What is FaithFi: Faith & Finance?
FaithFi: Faith & Finance is a personal finance app designed to connect everyday money management with Christian principles. It typically provides educational content, budgeting guidance, financial discussions, and faith-based resources intended to help users make more thoughtful decisions about spending, saving, giving, and managing debt. It is better viewed as a guidance and learning tool than as a replacement for a professional financial adviser.
02What features does FaithFi: Faith & Finance offer?
The app focuses on practical financial education through a faith-centered perspective. Depending on the current version and your region, you may find articles, podcasts, videos, devotionals, budgeting ideas, money-related discussions, and resources covering topics such as generosity, saving, debt, stewardship, and financial planning. The exact selection can change over time, so users should check the app’s latest store listing before downloading.
03Is FaithFi: Faith & Finance free to download and use?
FaithFi: Faith & Finance may be available to download at no initial cost, but some content, programs, memberships, or additional resources could require payment. Before creating an account or subscribing, review the pricing page, billing frequency, renewal terms, and cancellation policy carefully. Availability of paid features can vary between Android and iOS, as well as by country and app version.
04Can FaithFi replace a financial adviser or budgeting app?
FaithFi can be useful for learning about money and reflecting on financial choices through a Christian worldview, but it should not automatically be treated as personalized financial advice. It may complement a spreadsheet, banking tool, or dedicated budgeting application, yet it might not provide the same account synchronization, investment analysis, tax guidance, or debt-planning features. For major financial decisions, consult a qualified professional.
05Is FaithFi: Faith & Finance suitable for everyone?
The app is primarily intended for users who appreciate Christian perspectives on stewardship, generosity, and personal finances. Its content may be especially relevant to individuals, couples, families, or small groups seeking faith-based financial education. Users from other backgrounds can still find practical ideas, but some language and recommendations may be explicitly Christian. Parents should also review the app’s content and privacy information before allowing children to use it.


